
Controllers: 5 Steps to Regulator Ready Centralized Journal Posting

Centralized journal posting consolidates and automates ledger postings while preserving transaction-level audit trails and approval routing, delivering faster closes and stronger controls if designed for traceability. It cuts down on repetitive manual journals and speeds up the close, but only when it includes an audit trail, approval workflow, ERP posting logs, and a reconciliation loop. Without those elements, centralization just moves risk from many hands to one system.
TL;DR:
- Centralized journal posting is most beneficial for businesses handling thousands of transactions across multiple marketplaces or entities, where manual entry errors are more likely.
- A robust system must include an audit trail linking each journal to its source, approval routing with maker-checker controls, and automated validation to catch mismatches before posting.
- Implementation should follow structured stages, including data mapping, thorough testing, parallel runs, and only after achieving consistent results should manual processes be retired.
- Vendors or solutions must allow full traceability, generate automatic reconciliation reports, and enforce access controls to be considered audit-ready and compliant.
- BeanHawk offers a specialized tool for ecommerce settlement posting that maintains detailed source links and exception handling, ideal for multichannel sellers seeking accuracy without extensive internal development.
Table of Contents
- What centralized journal posting actually means
- Core features and controls a posting design needs
- Compliance expectations that make traceability non-negotiable
- Rolling out centralized posting without breaking your close
- Choosing the right posting approach or vendor
- Where BeanHawk fits for ecommerce settlement posting
- When centralization is the right governance call
- Free audit: a practical next step for ecommerce controllers
- Sources
- FAQ
What centralized journal posting actually means
Centralized journal posting means routing ledger entries from multiple sources, systems, or business units through a single, automated process instead of having individual teams key journals by hand. Decentralized posting relies on people in different departments or entities preparing and entering their own journals, often with inconsistent formats and no shared review step. Centralization replaces that patchwork with one consistent posting engine, one set of validation rules, and one audit trail.
There are three common posting models, and the choice affects both accuracy and how easy the entries are to trace later.
- Order-level posting records every individual transaction, which gives the clearest audit trail but produces the highest volume and the most reconciliation work.
- Settlement-level posting groups transactions by settlement or payout period, cutting volume while still tying each summarized entry back to its source batch.
- Summarized posting rolls up large numbers of transactions into a single journal line, which is efficient but risky unless the summary can be traced back to underlying detail.
Centralization tends to pay off once transaction volume, entity count, or marketplace complexity outgrows what a manual process can handle accurately. A single-entity business with a few dozen journals a month rarely needs it. A multichannel seller posting thousands of settlement events across several marketplaces usually does. It’s worth remembering that centralization is a controls decision, not a GAAP requirement: nothing in accounting standards mandates it, but the alternative, scattered manual entries with no consistent review, tends to be where errors hide.
Core features and controls a posting design needs
A centralized posting system is only as good as the controls built into it. Before adopting or building one, controllers should require the following.
- A machine-sensible audit trail that links every source record (order, invoice, settlement) to its journal voucher and the resulting general ledger posting, so any entry can be retraced to its origin.
- Approval routing with maker-checker controls, meaning the person who prepares an entry is never the same person who approves it, enforced through role-based access rather than an honor system.
- Automated validations and exception handling that flag mismatched amounts, missing references, or duplicate postings before they hit the ledger, rather than after.
- A documented reconciliation loop that compares posted totals against source system totals on a defined schedule and surfaces variances for review.
- ERP connectors with posting logs, including idempotent posting logic so a retried or resubmitted batch never creates a duplicate entry.
- Templates, batch processing, and scheduled posting with blackout windows around period-end close, so automated jobs don’t overwrite manual adjustments mid-close.
Automated recurring entries are common because most postings originate directly from transaction flows rather than manual keying, but that’s exactly why exception handling matters more, not less: when the system runs on autopilot, a broken rule can repeat for months before anyone notices.
Pro Tip: Build the exception queue before you build the automation. If you don’t know what “wrong” looks like, the system can’t tell you when it happens.
Compliance expectations that make traceability non-negotiable
Regulators and auditors don’t care how fast your close is if the underlying records can’t be retraced. The Internal Revenue Service treats machine-sensible ADP system records as books and records under Section 6001, meaning they must be retained and given the same evidentiary weight as paper records while material to tax administration. Separately, IRS guidance for small businesses makes clear that electronic bookkeeping systems must provide a complete, accurate record that’s accessible on request, with supporting documents retained and organized.
Auditors add another layer of scrutiny. The PCAOB’s staff guidance on journal entries instructs auditors to test recurring automated entries specifically because automation can create a false sense of security. A recurring journal that runs correctly for years can still be manipulated or broken without anyone noticing, so automation doesn’t eliminate management override risk, it just changes where the risk hides.
On the entity-level control side, the SEC’s interpretive release on internal control confirms that centralized processing is an acceptable control design under ICFR frameworks, provided management actively evaluates and monitors how well it operates across locations. Centralized processing doesn’t get a free pass just because it’s centralized.
A defensible setup keeps four artifacts on hand at all times: reconciliation logs tying postings to source totals, exception reports showing what got flagged and how it was resolved, approval history showing who reviewed what and when, and sampling results from periodic internal testing. Auditors will ask for these; controllers who can produce them immediately save weeks during fieldwork.

Rolling out centralized posting without breaking your close
Implementation should move through five stages, and skipping any of them tends to show up later as a reconciliation nightmare.
- Discovery and scoping. Identify which entities, accounts, and transaction types will run through the centralized process, and name the stakeholders who own exceptions.
- Data mapping and transformation rules. Define the reconciliation keys, unique settlement IDs, invoice numbers, or payment references, that every downstream check will rely on. Weak keys here are the single most common cause of failed audits later.
- Testing. Run unit tests on individual posting rules, integration tests across the full pipeline, and user acceptance testing with real historical data, then set clear acceptance criteria before moving forward.
- Parallel run. Operate the old and new processes side by side for a defined stabilization period, comparing outputs line by line rather than just checking totals.
- Cutover. Retire the manual process only once the parallel run has cleared without unexplained variances.
Timelines vary with complexity. A mid-market business with one ERP and a handful of accounts can often move from scoping to cutover within a single quarter; an enterprise with multiple entities and legacy systems should expect the process to stretch over several quarters.
Pro Tip: Underestimating the testing phase is the most common failure point. Budget more time for testing than for the technical build itself.
Common pitfalls include weak traceability (fix it by defining reconciliation keys before writing a single transformation rule), insufficient exception handling (fix it by building the exception queue before go-live, not after), and rushing the parallel run to hit a deadline (fix it by tying cutover to acceptance criteria, not a calendar date).
Choosing the right posting approach or vendor
Evaluating a centralized posting solution, whether built internally or bought, comes down to a short list of criteria that matter more than price or feature count.
- Traceability: can every posted entry be retraced to its source transaction without a manual side lookup?
- Audit evidence: does the system generate reconciliation logs, exception reports, and approval history automatically, or does someone have to reconstruct them after the fact?
- ERP integration: does it post natively to your general ledger with a visible log, or does it require manual export and import?
- Controls and access: does it enforce maker-checker separation and role-based access, or does one login have full authority?
- Exception tooling: are anomalies surfaced automatically, or do they surface only when someone notices the ledger doesn’t tie out?
- Scalability: does the model hold up as transaction volume or entity count grows, or does it require rework at each new threshold?
When talking to a vendor or an internal team, ask directly: can you show me a sample audit log from a real posting batch? What happens if the same batch is submitted twice? Who can approve a journal, and how is that enforced technically rather than just by policy?
The clearest red flags are an inability to produce a transaction-level retrace on demand, black-box summarization with no link back to source detail, and exception handling that only reports totals instead of specific anomalies.
| Criterion | Why it matters | What to ask |
|---|---|---|
| Traceability | Auditors and the IRS require retraceable records | Can you show a full trail from source to ledger? |
| Approval controls | Prevents single-person override | Is maker-checker enforced by the system or by policy alone? |
| Exception handling | Surfaces errors before they compound | Are anomalies flagged individually or only in aggregate? |
| ERP posting logs | Confirms what posted, when, and how | Is every post idempotent and logged? |
Weigh licensing cost against what manual reconciliation currently costs in staff hours and audit friction. A tool that costs more but eliminates a recurring manual reconciliation often pays for itself within a few close cycles.
Where BeanHawk fits for ecommerce settlement posting
BeanHawk was built around one specific version of this problem: multichannel ecommerce settlement posting. It automates posting of settlement data to QuickBooks and Xero while keeping the reconciliation artifacts, source links, and exception detail that the checklist above calls for, rather than dropping a single summarized number into the ledger. For sellers dealing with Amazon settlements, marketplace fee structures, and reimbursement claims across channels, that means penny-accurate postings that still tie back to the underlying settlement detail. Building this kind of traceability internally is possible, but for a business without a dedicated engineering team, a purpose-built tool tends to reach that standard faster than an internal project competing for the same resources.

When centralization is the right governance call
Centralization works when there’s a single owner accountable for the process, documented service-level expectations, and a clear escalation path when something breaks. It’s the wrong call for a business too small or too fragmented to support that governance, where a decentralized process with strong local review still beats a centralized one nobody maintains. The technology matters less than the discipline behind it: training, defined metrics, and someone whose job it is to notice when the numbers stop tying out.
, Tim
Free audit: a practical next step for ecommerce controllers
If reconciling settlements across marketplaces is eating into your close every month, the fastest way to see where centralized posting would help is BeanHawk’s free FBA reimbursement audit. It reviews your inbound shipment and ledger events for missed reimbursements, gives a sample reconciliation of what’s currently posting versus what should be posting, and flags the specific gaps worth fixing first.
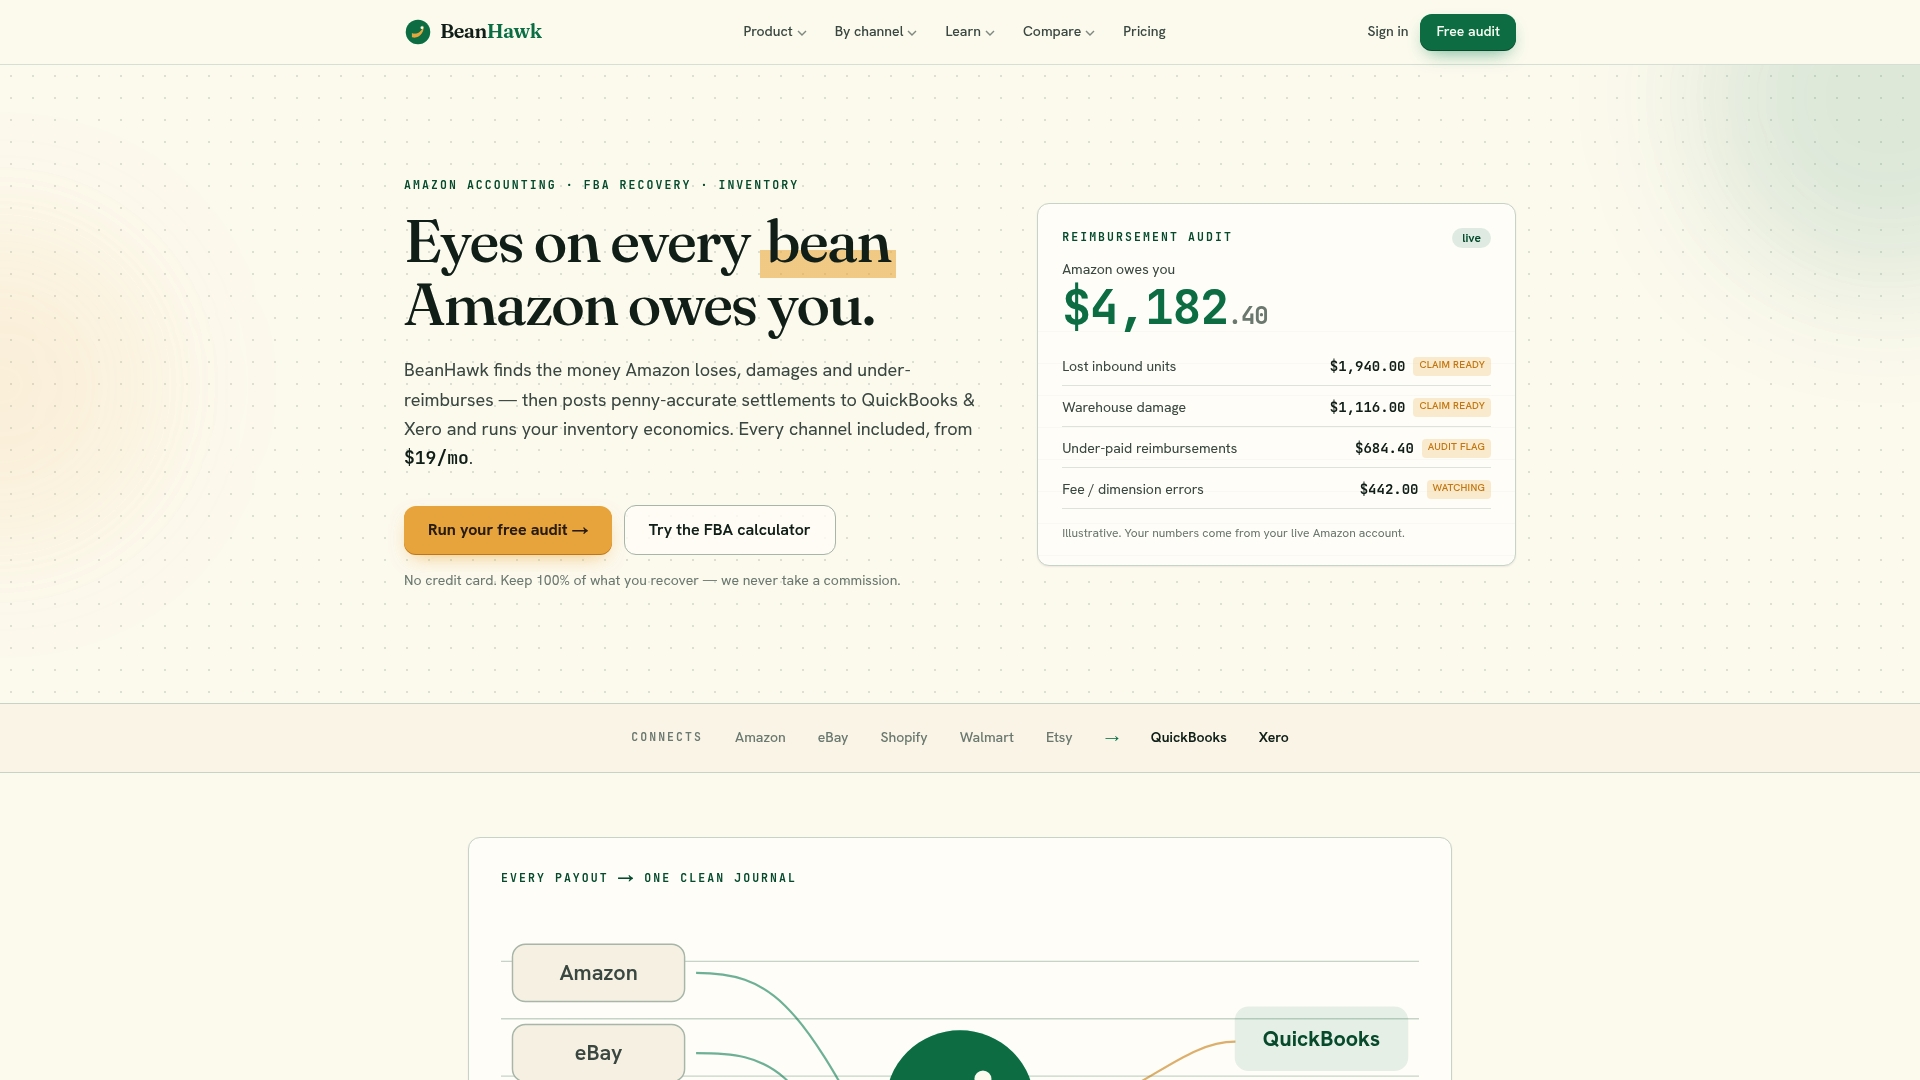
- The audit identifies posting gaps between marketplace settlements and your general ledger.
- You get a sample reconciliation showing what’s currently missed or misposted.
- Recommended fixes are prioritized by dollar impact, not just by volume.
From there, BeanHawk’s plans run from a Free tier up through Starter at $19 per month, Growth at $49 per month, and Scale at $99 per month, scaled to order volume, with no commission taken on recovered funds. Request the audit to see exactly where your current posting process is leaking accuracy.
Sources
- PCAOB , Audit focus: Journal entries
- Automated records | Internal Revenue Service
- How should I record my business transactions? | Internal Revenue Service
- SEC interpretive release on internal control (2007)
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What are the 7 types of journals?
Traditional bookkeeping recognizes several specialized journals, commonly sales, purchases, cash receipts, cash disbursements, payroll, and the general journal for adjusting and closing entries, though exact lists vary by textbook and industry. Most automated systems today consolidate these into a single centralized posting process rather than maintaining separate physical journals.
How are journal entries posted?
A journal entry is posted by transferring its debit and credit amounts from the journal into the corresponding general ledger accounts, either manually or through an automated system. In a centralized setup, this posting happens through validated, logged transactions that link back to the source document for later review.
Why are journal entries posted?
Journal entries are posted to update the general ledger so account balances reflect every transaction accurately and in order. This step is what makes financial statements possible, and it’s also the point where audit testing of automated posting logic matters most, since an unposted or misposted entry throws off everything downstream.
Does centralized journal posting replace the need for manual review?
No. Centralized posting reduces repetitive manual entry, but exception handling, approval routing, and periodic sampling still require human review to catch anomalies automation alone would miss.
What makes centralized posting audit-ready?
A setup is audit-ready when every posted entry can be retraced to its source transaction, approvals are logged with role-based access, and reconciliation reports are generated on a documented schedule rather than reconstructed after the fact.